

Mobile Home Insurance
A different policy form for a different structure, rated differently, with coverages a home policy does not offer.
Owners of a mobile or manufactured home.
- Owners who have never checked whether their home is classified as a mobile home or a manufactured home.
- Anyone about to move a home to a new site, where transit damage is a live exposure and an optional coverage.
- Owners whose coverage amount was set against a generic figure rather than against the home itself.
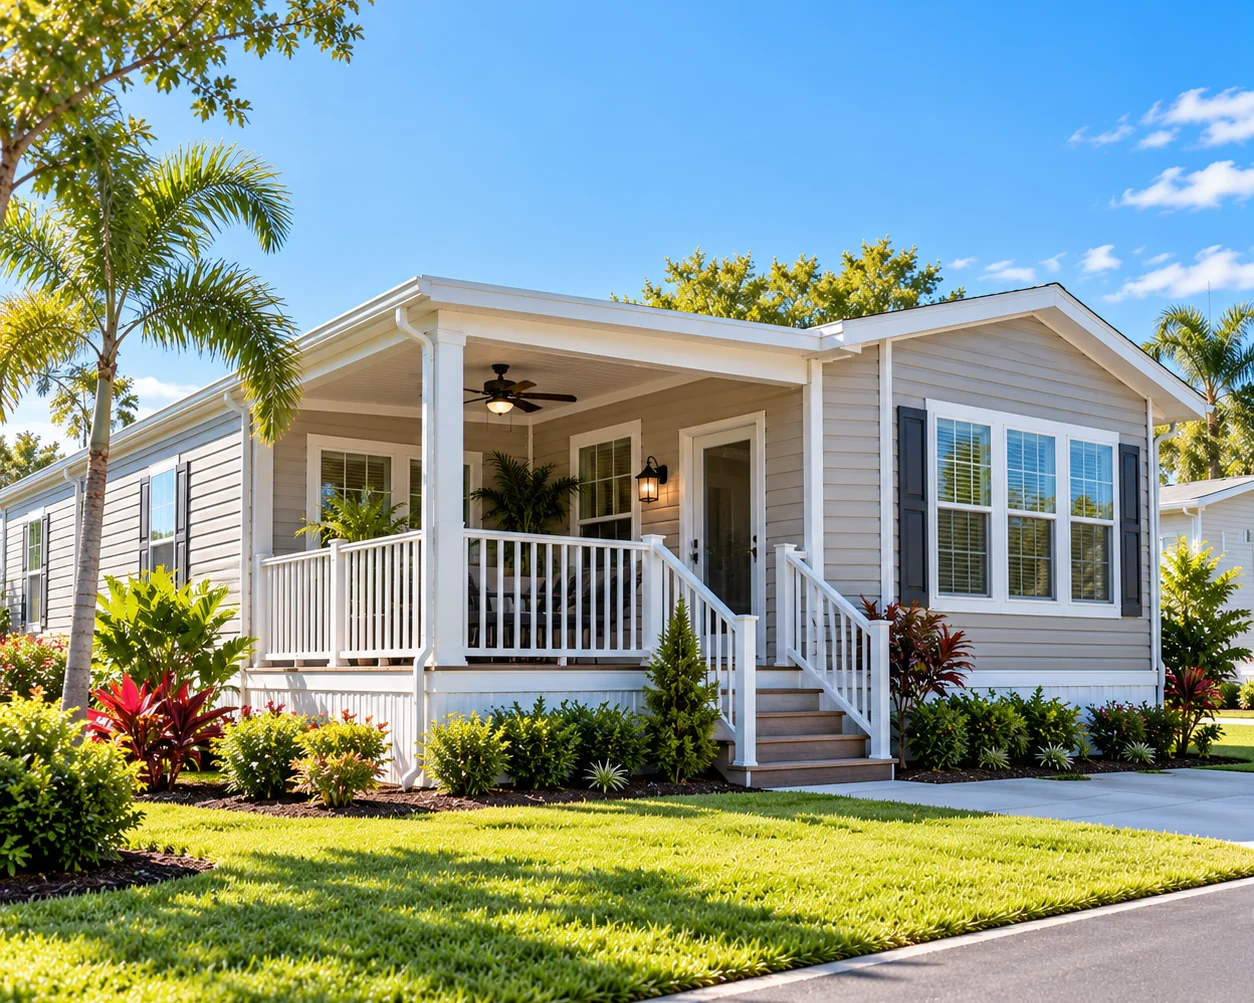
A mobile home carries more concentrated risk than a house, not less, and the specialty policy form exists for that reason.
Construction style means fire and severe weather can do serious damage quickly, and size means a single event is more likely to take the whole structure and everything in it rather than part of a building. A specialty policy can be written to the model and design of the home, which is the practical reason not to treat this as a homeowners policy under another name.
What the policy generally addresses
- The structure, written against its own value rather than the cost of a site-built house.
- Damage from covered natural disasters, including events more likely to damage a mobile home than a traditional house.
- Liability, including medical expenses for someone injured at the home.
- Damage while the home is being moved, normally an option rather than something included, so it is only there if it was asked for before the move.
The decisions that shape the policy.
- Check the manufacturing date first. It determines whether the home is treated as a mobile home or a manufactured home, and therefore which policy forms are available to you.
- Ask for the policy to be written to the home. A specialty policy can be tailored to the model and design of the specific home, which is a better starting point than a generic structure amount.
- What drives the premium. The value of the home, the local area, and the carrier writing it.
Mobile home questions we hear most
Is my home a mobile home or a manufactured home?
The manufacturing date settles it. Most mobile homes built after June 15, 1976 are classified as manufactured homes, and that classification can change the type of policy a carrier will offer.
Can I just insure it on a regular home insurance policy?
Sometimes, and if the home is classified as a manufactured home you may need to. A home insurance policy does not contain the same coverages as one designed for mobile homes, so the two are worth comparing rather than treating as equivalent.
Is the home covered while it is being moved?
Normally that is an option rather than something included, so it is only there if it was added. If a move is planned, it is worth confirming before the home leaves the site rather than afterwards.
Why does the manufacturing date matter?
It is the first thing to check, because it affects how the home is classified and how a policy can be written for it. The distinction between a mobile home and a manufactured home turns on it, and the two are not always treated the same way.
- Home Insurance
- Condo Insurance
- Renters Insurance
- Flood Insurance
- Auto Insurance
- Classic Car Insurance
- Motorcycle Insurance
- RV Insurance
- Off-Road & Recreational Vehicle Insurance
- Boat & Watercraft Insurance
- Umbrella Insurance
- Life Insurance
- High Net Worth Insurance
- Pet Insurance
- Event & Special Event Insurance
Let's put the right policy in place.
Oxford Risk LLC is an independent agency. We represent you rather than a single carrier, which means we can place your coverage with the company whose appetite actually fits your risk. Tell us what you need to protect and an advisor will take it from there.
- Call (330) 315-3081
- Hours Monday - Friday: 8:00 AM - 4:00 PM
- Offices Fairlawn, OH, Cranberry Township, PA, Columbus, OH, Livonia, MI